To track your music income, route every payment into a single ledger that records who paid you, which rights the money covers, the usage period it belongs to, and the date it arrived. Income from distributors, PROs, mechanical collectors, sync buyers and venues then becomes one number you can budget and report instead of a folder of unread PDFs.
It takes about an hour to set up properly and twenty minutes a month to keep current. The hard part was never the spreadsheet. It is knowing which payments are late because the payor runs on a schedule, and which are late because your metadata is wrong.
I have rebuilt this system twice for my own projects, and both times the same three numbers finally answered questions I could not settle from any single statement: what earned most, what was still missing, and what to hold back for tax.
Table of Contents
- What You Need to Track Your Music Income
- Step-by-Step: A Monthly System for Tracking Your Music Income
- Step 1: Choose One Central Tracker for Your Music Income
- Step 2: Collect Statements From Every Income Source
- Step 3: Record Each Payment and Its Details
- Step 4: Separate Gross Revenue From What You Actually Receive
- Step 5: Reconcile Reports and Investigate Differences
- Step 6: Review Trends and Make Decisions
- A sanity check worth running on every statement
- Common Mistakes
- Frequently Asked Questions
- Conclusion: Start This Week
What You Need to Track Your Music Income
You need four things, and none of them are software. Most artists who struggle with this are missing a decision, not a tool.
First, one central place to write things down. A spreadsheet works. So does a dedicated accounting app if you already keep your expenses in one. What does not work is a folder of PDFs and a note in your phone.
Second, the identifiers attached to your work: an ISRC for each recording, an ISWC for each composition, and a UPC or catalogue number for each release. Without these you cannot ask a payor to trace a specific payment, and the query gets vague enough that it goes nowhere.
Third, working logins for every organisation that already pays you or should pay you. That means your distributor, your PRO if you have one, your mechanical rights collector, your digital performance registration, your publishing administrator if you use one, plus the ad revenue portals on the video platforms where your music is fingerprinted.
Fourth, a separate account for tax. Music income arrives in lumps and the amounts do not predict each other, so income that lands in the same account you spend from is money you will accidentally spend twice.
A folder structure that holds up: one folder per payor, one subfolder per calendar year, and every downloaded CSV kept alongside the PDF of the same statement. When a payor’s reporting changes or you need to prove a figure, the raw export is the thing that saves you.
Step-by-Step: A Monthly System for Tracking Your Music Income
Step 1: Choose One Central Tracker for Your Music Income
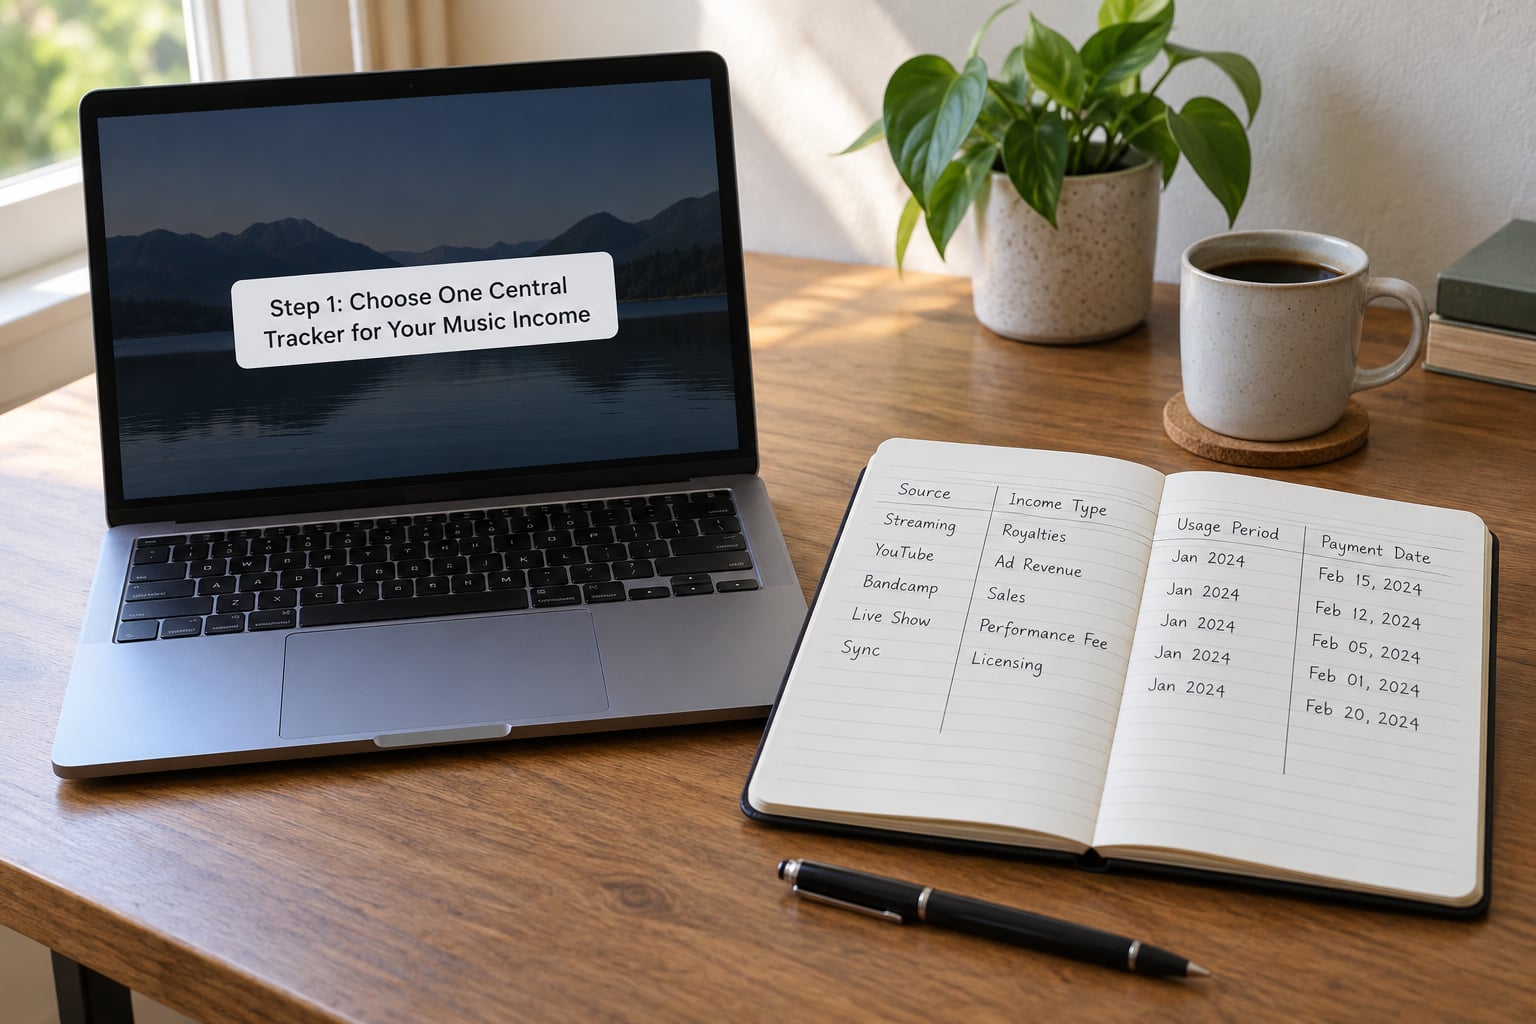
Pick the tracker based on how many income sources you have, not on how serious your career is. If money arrives from one distributor, one PRO and occasional session work, a spreadsheet handles it and most other options add friction you will not use.
Move up a level when the count crosses a few lines. Light bookkeeping software earns its place once you are recording expenses properly for tax and want the ledger to double as a set of books. Royalty accounting software built for labels and publishers earns its place when you are administering other people’s money or a back catalogue large enough that manual matching costs you real hours.
| Income source | Rights type | Where the statement lives | Typical lag |
|---|---|---|---|
| Streaming (DSP) | Master, via distributor | Distributor dashboard and monthly or quarterly export | Days to a few months, depending on distributor |
| Downloads and digital sales | Master, via distributor | Same dashboard, different row types | Varies with distributor |
| Performance royalties | Composition | Your PRO member portal | Often 6 to 9 months after the performance |
| Digital performance | Sound recording | SoundExchange dashboard | Quarterly, after the usage period closes |
| Mechanical royalties | Composition | The MLC or your mechanical collector portal | Roughly 75 days after the usage month |
| Sync and licensing | Master and composition | Your own invoices and contracts | On delivery, then backend on air |
| Video platform ad revenue | Master, via Content ID | Platform partner dashboard, if you use one | Monthly or quarterly |
| Gigs, teaching, merch | Your own business | Point of sale, invoices, bank statement | Same week |
One warning about the table above. Lag times are how the payors describe their own process, not guarantees. What matters is that they are long enough that a quiet month is normal, and that you record the usage period separately from the payment date so you can tell the two apart.
Step 2: Collect Statements From Every Income Source
Download on a schedule rather than when you remember. Streaming and digital performance statements suit a monthly check. PRO distributions, mechanical royalties and publishing statements suit a quarterly sweep, because that is roughly when they arrive anyway.
For each document, keep three things: the reporting period it covers, the payment date, and the file itself. The reporting period is the field people skip, and skipping it is what makes a year of records impossible to read later.
Registering an account is not the same as registering your works, and the difference is where money disappears. If your compositions sit with a PRO but no performance was ever logged against them, the money is real and unclaimed, and no statement will ever show it. A quick check that your works appear in your PRO member portal is worth more each quarter than any spreadsheet tweak.
Step 3: Record Each Payment and Its Details
One row per payment per payor. Not one row per month, and not one row per release. A single distributor statement for a quarter can contain six releases and two different revenue types, and collapsing that into one line destroys the detail you need later.
These are the columns worth having:
- Date received
- Payor, the organisation that sent the money
- Income type, using a fixed list you never extend mid-year
- Release or work the money relates to
- Identifier, the ISRC, ISWC or catalogue number
- Usage period the money was earned in
- Gross amount
- Deductions
- Net amount received
- Currency, and the exchange rate if you convert
- Location of the saved statement
- Status, whether it is matched, queried or unexplained
A filled row looks like this: payor, a distributor; income type, streaming; release, a recent single; identifier, an ISRC; usage period, the first three months of 2026; gross, the amount before the distributor’s commission; deductions, the commission withheld; net, what landed in the bank; status, matched.
Keep the income type list short and boring: streaming, downloads, digital sales, performance royalties, digital performance, mechanical royalties, sync, licensing, gigs, teaching, merchandise, fan funding, other. A fixed list is what makes a pivot table possible in December.
Step 4: Separate Gross Revenue From What You Actually Receive
Your net number is the one that matters for tax and for deciding whether a release is worth pushing further. But a net number alone hides problems, so keep both columns and read the gap between them.
The deductions you will meet most often:
- Distributor commission, usually a percentage taken off the top before splits apply
- Writer and producer splits, where a split sheet assigns part of the composition income to other people
- Publisher share, if a publishing administrator is involved
- Withholding tax on payments from outside your country of residence
- Recoupable costs and advances, which reduce later payments until they clear
A split sheet you signed eighteen months ago is not the split sheet you remember. Keep the current version of every split sheet with the ledger for the releases it covers, and when a payment comes in lower than expected, read the splits before assuming the payor made an error.
The reverse check also matters. If gross is identical month after month, you may be copying a static figure rather than the real statement, and a flat gross hides a falling audience better than any dashboard.
Step 5: Reconcile Reports and Investigate Differences
Once a month, run the same five checks. The value is in repeating them, because the first month finds problems and the fifth month finds patterns.
- List every organisation that should pay you, and tick off each one that produced a statement this period.
- Confirm your works are registered, not just your accounts. Check that the titles and identifiers in the portal match your own catalog file.
- Pull the latest statement and note the usage period it covers.
- Compare territories and platforms in the statement against what your usage figures imply should have paid.
- Take each gap to the organisation holding it, with ISRCs and ISWCs in hand.
Step five is the one people skip, and it is where the money is. A query with a specific identifier and a specific period gets answered. A query that says you think you are owed something gets a template reply.
Do not treat every quiet month as a problem. An empty January is expected when mechanical royalties run roughly 75 days behind the usage month, and a PRO distribution that arrives quarterly reflects performances from earlier quarters. Judge each payor against its own schedule before you start chasing it.
One bucket needs deliberate handling: Content ID and video platform ad revenue. It rarely appears in a distributor statement or a PRO statement, so if you never look at that dashboard separately, months of it can go unrecorded while everything else looks fine.
Step 6: Review Trends and Make Decisions
Once the ledger has three months in it, start slicing it. By release, by platform, by territory, by income type, by month. Two questions come out of that almost every time: which territories are actually paying, and which release is quietly out-earning your newest one.
Use the results for decisions you can act on. If one platform carries most of your income, your playlist and release-day effort belongs there. If sync and licensing is a real share of your ledger, it deserves a monthly hour rather than a quarterly scramble, because those deals turn on tracking terms and deadlines rather than on volume.
Do not treat one payment period as a trend. A sync fee, a catalogue advance and three months of streaming will make any single quarter look like a turning point. Read quarters, not weeks.
A sanity check worth running on every statement
Independent streaming rates move, but the order of magnitude does not. A useful benchmark: roughly 250,000 streams on an independent release has historically landed somewhere near a thousand dollars before any commission or splits. Use it as a smoke alarm. If a statement for 40,000 streams shows a payout that looks like a year’s income, you have a metadata problem, not a good month.
Run the same check against ad revenue and against any per-play figure a promoter quotes you. Outliers are almost always metadata, split or territory issues, and they are cheaper to find in the ledger than at tax time.
Common Mistakes
Here are the errors that quietly distort the record, and the fix for each.
Recording only what arrived. A payment with no usage period tells you nothing about whether it is on time. Add the period and the comparison becomes possible.
One row per month per payor. Six releases in one quarterly statement become one meaningless line. One row per payment keeps releases, territories and revenue types separate.
Renaming income types whenever you find a new one. Fixed categories are what make a year of records sortable. Add a new type only at the start of a quarter.
Deleting statements you have already logged. The archive is the backup. Keep every PDF and CSV, stored by payor and year.
Chasing payments that are simply early. Build the lag table above into your expectations, and check each payor against its own schedule rather than against the loudest account in your inbox.
Trusting the net figure and ignoring gross. A net number that quietly shrinks over months is often a split or recoupable cost you stopped reading. Keep both columns.
Mixing tax set-aside with spending money. Move the set-aside on the day income lands, not at the end of the quarter. Irregular income makes procrastination expensive.
Assuming registered accounts mean registered works. Unmatched money usually traces back to works that were never logged, not to payors withholding it.
Beyond fixing errors, three habits keep the system alive. Review monthly, even in a month where nothing arrived, because that is when the lag table proves itself. Back up the folder monthly to a second location, since statements arrive as downloads that vanish with a reinstall. And keep your ownership documents with the ledger: split sheets, registration confirmations, delivery receipts and contracts, filed by release.
That last one pays off more often than it sounds. When a publisher or a sync buyer asks for documentation on a deal from a few years back, having the paperwork filed by release turns a week of searching into an email.
If the paperwork is going to an accountant or a manager, hand over the ledger, the folder of statements and the ownership file together. Splitting those three across inboxes is how gaps get lost, and the reconciliation work usually has to be redone. Tax handling varies by country and by how you are registered, so confirm the position for your own situation with a professional before you file.
Frequently Asked Questions
How do I keep track of royalties in music?
Put every payment into one ledger with one row per payment, and record four fields that are easy to skip: the payor, the income type, the usage period the money was earned in, and the date it arrived. Download statements on a schedule, keep the PDF and CSV of each one in a folder named for the payor, and review once a month against the lag that payor normally runs. Regularity matters more than software choice.
What is the best accounting software for musicians?
For one distributor, one PRO and occasional session work, a spreadsheet is genuinely enough. Move to light bookkeeping software once you are tracking expenses for tax and want the ledger to double as records. Royalty accounting software built for labels and publishers only makes sense when you are administering other people’s money or a catalogue large enough that manual matching costs real hours. Do not buy label tooling for a personal release.
What expenses can you write off as a musician?
Common deductible categories include recording and rehearsal space, studio time and engineer fees, instruments and repairs, software subscriptions, computers used for production, music stands and accessories, travel to performances or sessions, promotion and advertising, merchandise materials, and professional membership or union dues. Rules differ by country and by how you are registered, so check the current position with a tax professional before relying on any of it.
How much money is 50,000 streams on Spotify?
At independent rates, 50,000 streams on a single platform has historically landed somewhere in the low hundreds of dollars, before distributor commission, writer splits and any publishing share. Rates change with subscription pricing and listen-through, so treat any figure as a range rather than a rate card. The useful habit is comparing your own statement against your own history, since one platform pays more than another for the same play.
How many streams does it take to make a thousand dollars?
Using the long-running independent benchmark of about 250,000 streams per thousand dollars, a thousand dollars takes roughly a quarter of a million streams on one platform. Spotify, Apple Music and YouTube Music pay differently, and your distributor takes a commission before splits apply, so the same stream count produces different totals depending on where it played. Use the benchmark to catch outliers, not to forecast income.
Why do my royalty statements arrive months apart?
The lag comes from the payor’s process, not from you. Mechanical royalties run roughly 75 days behind the usage month, PRO distributions often land 6 to 9 months after the performance and reflect quarters earlier, and streaming statements follow the distributor’s own schedule. Because usage period and payment date are separate fields in your ledger, you can tell a late-but-normal payment apart from one that never arrived at all.
Conclusion: Start This Week
Pick one hour this week. Build the ledger with the twelve columns, open a folder for each payor you already receive money from, and download every statement you can find from the last two quarters.
Then do the unglamorous part: check that your works are registered in your PRO member portal and that your split sheets match what you are actually being paid. That single check catches more lost money than any app you could buy.
From 2026 onward, the monthly rhythm is twenty minutes, a fixed day, and the discipline of writing the usage period every time. That habit is what turns scattered payments into a business you can actually plan around.